Business insurance for construction and trades
The insurance a construction or trades business needs: liability for damage at the customer's, tools and machinery, the company van and the requirements in AB 04 and ABT 06.
In construction and the trades, the biggest risk is damage at the customer's: a pipe that bursts, a fire during roofing work or a scratched facade. That makes liability insurance one of the most important covers, and often a requirement in the contract. Beyond that, most businesses need cover for tools and machinery, the company van and disputes about the work.
The biggest risk in construction
A construction or trades business works in other people's homes, premises and buildings. So a mistake often becomes damage to someone else's property, and that can be expensive. A water leak can ruin the floors in several flats, and a fire during roofing work can spread to the whole building.
The second risk is your own equipment. Tools and machinery are left in the van, in a container or on site overnight, and theft from building sites and work vans is common. When the machines are out of action, so is the job.
The third is disputes. Disagreements over extra work, delays and defects are common, and a dispute over a final invoice can drag on for a long time.
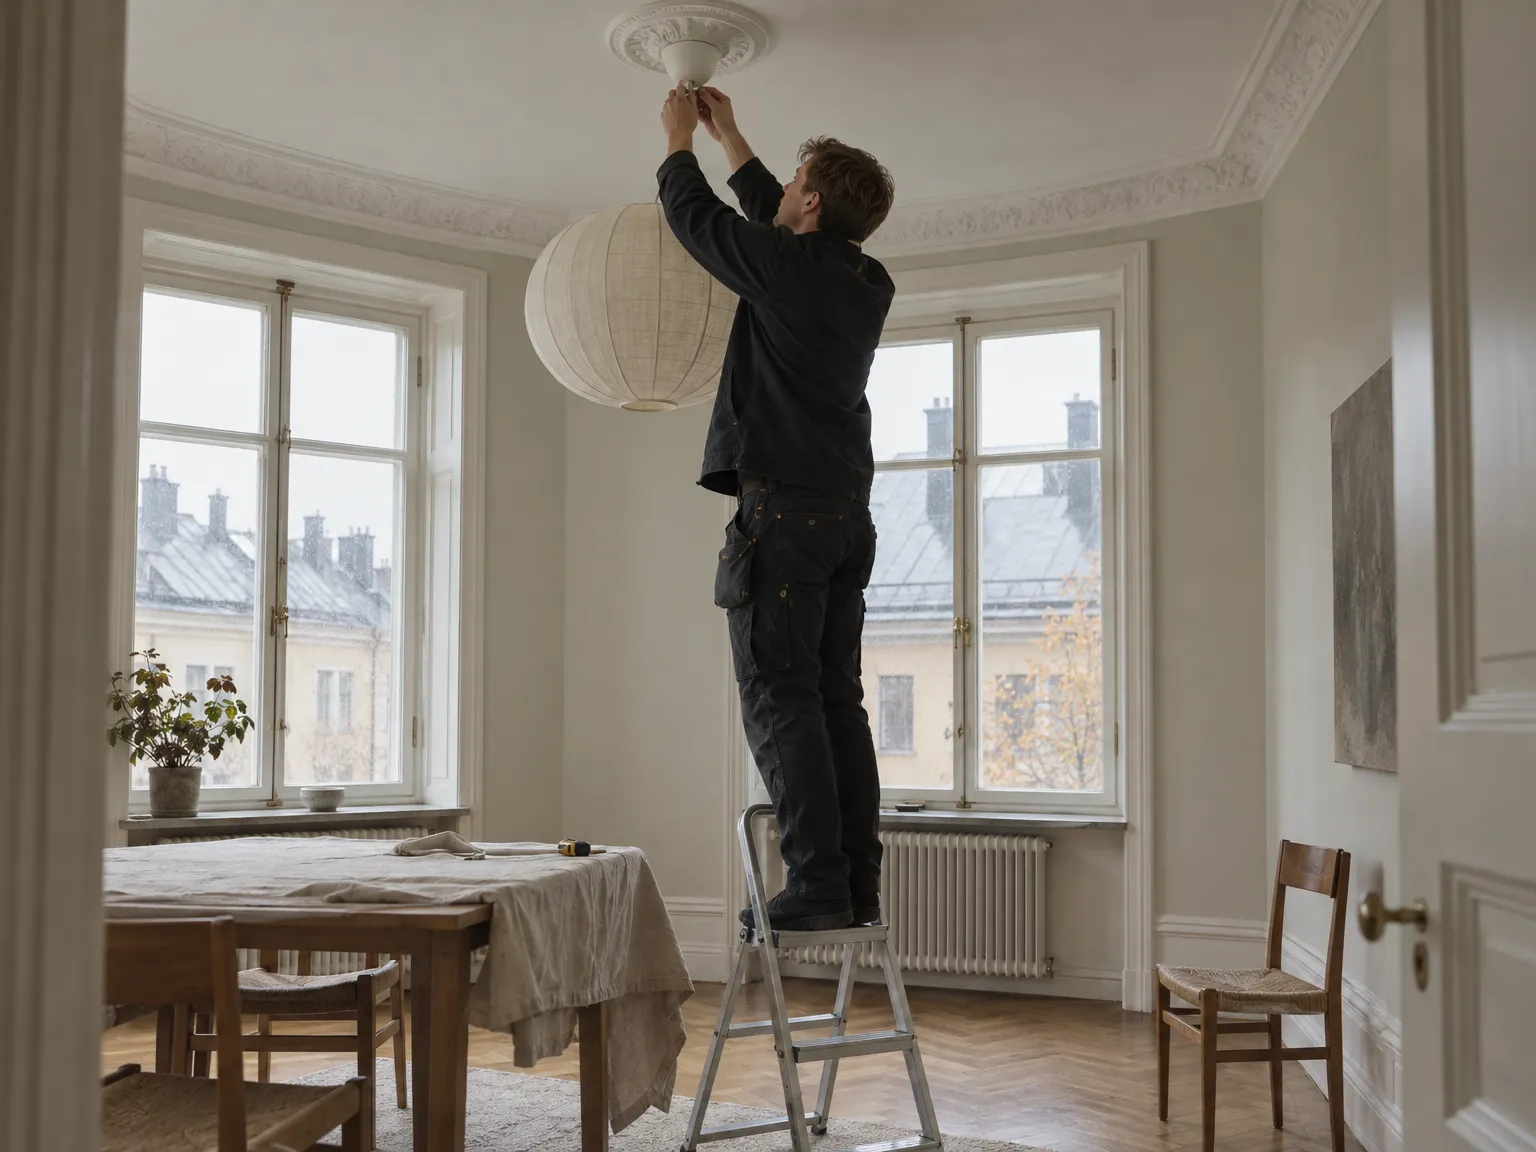
Example: The pipe behind the wall. An electrician drills for a new socket in a bathroom and hits a water pipe in the wall. The water runs down into the flat below before anyone notices, and the neighbour's ceiling and floor have to be replaced. The liability insurer investigates and pays for the neighbour's damage, minus the deductible. Repairing the electrician's own work is usually the company's cost, see the question about the work itself below.
What most construction and trades businesses need
Liability
Pays for damage you cause to the customer's or anyone else's property, or to a person, while you carry out the work. Read more about liability insurance. Check that the limit is high enough for the jobs you take on, and what applies to damage to the work you are doing itself.
Property: tools and machinery
Pays for tools, machinery and materials that are damaged or stolen, including on site and in the van if the policy terms say so. They often have to be locked away. Read more about property insurance.
Vehicles
The company van needs trafikförsäkring, the third-party motor cover, by law, and most businesses add part or comprehensive cover on top. Read more about motor insurance.
Legal protection
Pays part of the cost of lawyers and court proceedings if you end up in a dispute with a customer or a subcontractor. Read more about legal protection insurance.
Larger projects often add contractors' all risks insurance (entreprenadförsäkring), which pays for damage to the building works themselves during construction.
What customers and contracts require
- AB 04 and ABT 06. When the Swedish standard construction contracts are used, they require the contractor to have liability insurance, and often all risks insurance for the works. Read the insurance clause in the contract and check that the amounts match.
- Completion guarantee. When you build or renovate a one- or two-family house for a private customer, the law often requires a completion guarantee (färdigställandeskydd). It protects the customer if you cannot finish the job.
- Hot work. Anyone who welds, solders or works with an open flame usually needs a hot work certificate under the policy terms. If the rules are not followed, the payout can be cut sharply if a fire starts.
- Collective agreements. If the company is bound by a collective agreement, it includes agreement-based insurances for employees that the employer must take out.
How much does it cost?
The price mainly depends on what you do, how many you are, turnover and how high the limits you need are. An electrical contractor and a painter have different risks and different premiums. For more on pricing, see how much business insurance costs.
SNI codes
SNI is the Swedish industry classification. This page covers companies with these codes:
- 41200 Construction of residential and non-residential buildings
- 43120 Site preparation and groundwork
- 43210 Electrical installation
- 43221 Heating and plumbing work
- 43320 Joinery installation
- 43341 Painting
- 43910 Roofing
- 43999 Other specialised construction activities
Frequently asked questions
Does liability insurance apply if I make a mistake in the work itself?
Usually not for the work itself. Liability insurance pays for damage the work causes to other things, such as the neighbour's ceiling after a leak. Redoing work that was done wrong is usually the company's own cost.
Are my tools insured in the van overnight?
It depends on the policy terms. Many policies only pay for theft from a vehicle if the tools were locked away and out of sight, and sometimes only up to a lower amount. Check your försäkringsbrev (the policy document).
Do I need my own insurance as a subcontractor?
Yes, as a rule. The main contractor's insurance usually does not cover damage you cause, and the contract often requires you to have your own liability insurance.
What applies when I hire machinery?
You are often responsible for the hired machine. Check whether the hire agreement requires insurance, and whether your property insurance covers hired property.